

Fifth Third: 53 Mobile Banking

- 34.94K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on Fifth Third: 53 Mobile Banking from Appgk
Fifth Third: 53 Mobile Banking is the kind of finance app I judge less by its first few minutes and more by what happens after the novelty disappears. A banking app does not need to entertain me; it needs to help me check money, move through routine tasks, and leave me confident that I understood what happened. After using this app as a daily banking companion, I found its strongest quality in that practical rhythm. It is built for customers of Fifth Third Bank who want their account access available on a phone rather than tied to a branch visit or a desktop browser.
The app is free, developed by Fifth Third Bank, and aimed at everyone from a content-rating perspective. Its long presence on mobile, beginning in late 2011, also matters here: this is not a new experiment trying to prove that a bank belongs on a phone. It has had time to become part of ordinary account management. The store summary, “If your phone is on, your bank is open,” captures the central idea, but the real question is whether that convenience remains useful when I am checking balances for the tenth time in a month.
How 53 Mobile Banking Holds Up Beyond the First Week
The first-week appeal is simple and practical
My first impression is that the app makes sense when I approach it with a specific banking job in mind. I am not opening it to browse; I am opening it because I want to see whether a payment cleared, check the available balance before buying something, or confirm that money moved where I expected. That narrow purpose works in its favor. A finance app becomes frustrating when it makes routine information feel hidden behind unnecessary decoration, and 53 Mobile Banking is most convincing when it stays focused on access.
The app’s large audience suggests that this basic approach resonates. It has passed one million installs and holds a 4.7 average from roughly 217 thousand ratings, with about 35 thousand written reviews. I treat those figures as useful context rather than a guarantee: a high average does not tell me whether the app fits my banking habits, and a large install count does not make it appropriate for someone who does not bank with Fifth Third. Still, they indicate that this is an established mobile banking tool rather than a niche companion.
Best Parts of Fifth Third: 53 Mobile Banking
Things to Keep in Mind About Fifth Third: 53 Mobile Banking
During an ordinary first week, the most valuable habit is checking the account before making a decision, not after. For example, imagine I am at a grocery store and cannot remember whether a recent bill has already reduced my balance. Opening the app before paying gives me a current point of reference and may prevent an avoidable overdraft decision. That is not a flashy feature, but it is the kind of small intervention that gives a banking app lasting value.
I also like the difference between checking information and taking action. A quick balance check should not feel like I am beginning a complicated banking session. Conversely, a transfer or payment deserves more attention because a mistake has consequences. My advice is to use the app casually for observation but slow down whenever money is being moved: verify the account direction, the amount, and the timing before confirming. That workflow is more important than learning every screen.
News and Features Related to Fifth Third: 53 Mobile Banking

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Who will find the app immediately useful?
This is a natural fit for existing Fifth Third customers who prefer handling routine banking from an Android or iOS device. It is especially useful for someone whose schedule makes branch visits inconvenient, someone who wants a quick view of spending before leaving home, or someone who wants to replace a desktop-only banking routine with a phone-based one. The free price removes a separate subscription decision, so the real cost is attention: I need to keep my login habits sensible and remember that convenience does not replace checking details.
It can also suit people who want one dependable place for recurring money checks rather than a separate budgeting service. I would not expect it to replace a dedicated financial planning tool for someone who wants deep analysis across several banks, investments, debts, and household goals. A bank’s own app is usually strongest around that bank’s accounts and services. If my financial life is spread across many institutions, a broader aggregation or budgeting product may offer a more complete picture, even if it is less direct for Fifth Third account actions.
Don't want to read the full review?
There is another important boundary: this is not a universal banking app. If I do not have a Fifth Third relationship, installing it does not create a useful account-management experience. That sounds obvious, but it is worth stating because the store’s broad availability can make any finance app look generally applicable. Here, the developer and the bank are the same organization, which is an advantage for customers who want a direct connection to their bank and a reason to skip it for everyone else.
What creates month-to-month value?
After the first week, the app earns its place through repetition. I can imagine opening it on payday, before a large purchase, after a scheduled payment, and whenever an unexpected transaction appears in a notification or statement. None of those moments is remarkable on its own. Together, they form a useful financial routine: check what changed, decide what needs attention, and close the app once the question is answered.
Screenshots
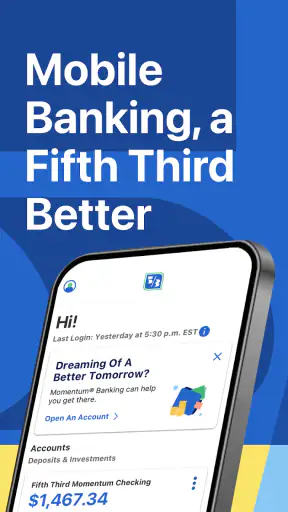
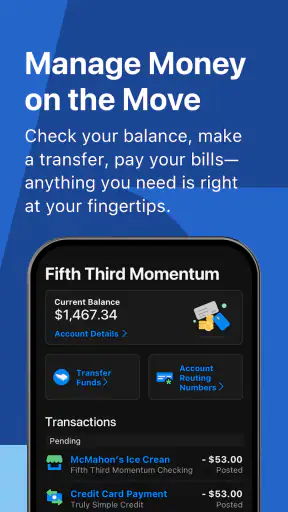
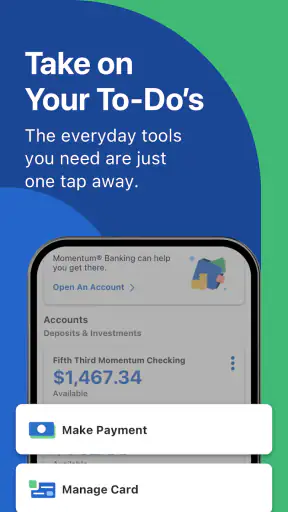
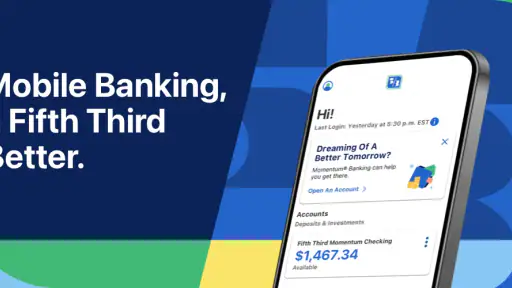
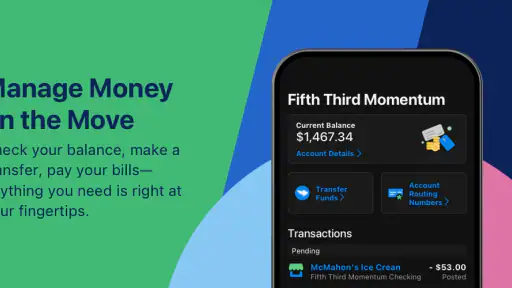
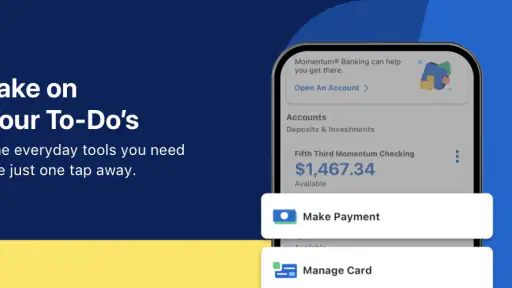
The most effective long-term use is to attach the app to existing habits. I would check it after reviewing household bills, before transferring money between accounts, and at the end of the week when reconciling purchases. This is better than opening it randomly throughout the day, because repeated anxious checking does not necessarily improve financial control. The app helps most when I use it as a checkpoint rather than as a constant source of reassurance.
A less obvious benefit of a bank-specific app is context. When I am looking at Fifth Third accounts through the bank’s own mobile channel, I do not have to translate a third-party service’s labels or wonder whether a delayed connection is showing stale information. That does not mean every display is instantly self-explanatory, but it gives the information a clear home. For routine account awareness, that directness is often more valuable than a larger collection of optional dashboards.
There is a useful trade-off here. A specialized banking app may feel less comprehensive than an all-in-one money manager, but it can also create less friction for the one institution I use most. I would choose 53 Mobile Banking for direct access and choose a broader finance tool alongside it if I needed cross-bank planning. The two purposes are different, and expecting one app to perform both perfectly is a common source of disappointment.
Maintenance is light, but not invisible
The current version is 5.26.0, and the app requires at least OS version 9. That makes compatibility a practical part of the decision. On a reasonably current device, I would treat updates as routine maintenance rather than something to avoid. Banking software handles sensitive tasks, so staying on a supported version is more sensible than keeping an old installation simply because it feels familiar. At the same time, anyone using an older phone should check compatibility before building a daily routine around it.
My maintenance advice is straightforward: keep the app updated through the normal device process, use a screen lock, and do not treat a remembered login as permission to stop paying attention. A banking app can make access easier, but the phone itself becomes part of the security chain. I would also avoid doing important transactions while distracted or on an unreliable connection. If a screen takes longer than expected, I would wait for the result and verify the account activity rather than immediately repeating the action.
The app’s free status is helpful because maintenance does not come with an additional app fee. That does not mean every banking action is automatically cost-free; the app is a channel for banking, not a promise about every account term. I would still read the confirmation screens and account information carefully, especially for transfers, payments, or anything scheduled for a later date. The right long-term attitude is convenience with verification.
One practical limitation is that mobile access cannot solve every banking question. If I need a complex explanation, a correction, or help with an unusual account issue, I may still prefer direct support or another official banking channel. The app is excellent at reducing the number of reasons I need those channels, but it should not be judged as a complete replacement for human assistance in every situation.
Where recurring fatigue can appear
The first source of fatigue is repetition itself. A mobile banking app asks me to perform similar checks again and again, and there is no novelty to carry me through a dull month. That is not a defect unique to this product; it is the nature of banking. Still, the experience can feel tiring if I expect the app to organize my entire financial life instead of simply helping me answer immediate account questions.
A second source is the mental pressure attached to financial actions. A banking screen can be visually simple and still make me cautious because I know that a wrong amount or destination matters. I consider that caution healthy, but it means the app should be used deliberately. I would not rush through a transfer while walking, and I would take an extra moment to confirm details before submitting anything that cannot be casually undone.
There is also the fatigue of switching tools. Someone who tracks spending in a spreadsheet, uses a budgeting service, and manages several banks may find that 53 Mobile Banking adds another place to check. In that situation, the app remains valuable for direct account access, but it may not become the main financial dashboard. A person who wants automatic category analysis, long-range projections, or a unified view may be happier using a dedicated planning product and opening this app only for Fifth Third-specific confirmation.
Finally, the app is not the right choice for someone looking for a general-purpose finance experience without a Fifth Third account. Its identity is its strength and its limitation. The bank-specific connection makes it relevant to customers of Fifth Third Bank, while making it unnecessary for people who only want a generic expense tracker or a multi-bank overview.
Small workflows that make it more useful
I found three habits more valuable than simply knowing that the app exists. First, I would use a “before and after” check for important activity: look at the balance before a transfer or payment, complete the action carefully, and return later to confirm the resulting transaction. This creates a simple personal audit trail without requiring a separate system. It is especially helpful when several bills or purchases happen close together.
Second, I would use the app as a weekly reconciliation checkpoint rather than relying only on memory. I can compare recent account activity with receipts, subscriptions, and planned bills. The point is not to stare at every transaction daily; it is to catch unfamiliar activity while it is still easy to remember what happened. This workflow turns a quick banking app into part of a broader money-management habit.
Third, I would separate urgent checks from planning sessions. If I only need to know whether I can afford today’s purchase, I would keep the visit brief. If I am preparing for rent, a large bill, or a transfer, I would sit down and review the relevant details without multitasking. That distinction reduces mistakes and prevents the app from becoming an anxious reflex.
These habits also show why the app’s lasting value is not measured by how many minutes I spend inside it. A successful banking app may lead me to complete a task quickly and leave. The shorter the useful visit, the better, provided I leave with the right information and a clear understanding of what I confirmed.
How it compares with ordinary alternatives
The most obvious alternative is a desktop browser. A website can be more comfortable when I am reviewing several items at once, typing extensively, or working with a larger screen. The mobile app wins when I need a quick check away from my desk. I would use the phone for everyday awareness and reserve a browser or direct support for situations where a larger workspace or more detailed explanation helps.
A second alternative is a third-party budgeting app. That kind of tool may be better for combining accounts, categorizing expenses, and viewing long-term patterns. 53 Mobile Banking has a different advantage: it is the direct mobile doorway to Fifth Third. For accuracy around the bank’s own account activity and for routine access, I prefer the bank-specific app. For a household budget spanning multiple institutions, I would not rely on it alone.
The final alternative is doing nothing on mobile and visiting a branch or calling the bank for every question. That can make sense for complicated or sensitive matters, but it is inefficient for a balance check or routine review. The app earns its space by handling those small jobs without turning them into appointments. Its value is not that it eliminates personal banking support; it keeps support available for the issues that genuinely need it.
Long-term verdict: useful when it becomes a habit
After the initial appeal fades, Fifth Third: 53 Mobile Banking remains worthwhile because its purpose is naturally recurring. I do not need a new feature every week to justify keeping it installed. I need dependable access to my Fifth Third banking routine, a quick way to verify what changed, and enough clarity to make careful decisions. The app’s 4.7 average, broad adoption, free availability, and established history support that practical case, while its latest version and OS requirement remind me to treat updates as part of responsible use.
My recommendation is strongest for Fifth Third customers who want mobile access without turning banking into a complicated project. I would keep it on my phone, connect it to a weekly review, and use it for quick checks before meaningful purchases or payments. I would not recommend it as the only financial tool for someone managing several institutions or seeking advanced budgeting analysis. In that case, it works better as the authoritative Fifth Third account channel beside a broader planning app.
The lasting test is whether the app reduces friction without encouraging careless speed. In my experience, it passes when I use it with a few deliberate habits: verify important actions, review activity regularly, keep the app maintained, and know when a browser or human support is more appropriate. That balance is why it feels less like a novelty and more like a practical part of everyday banking.
My final view: this is a focused, sensible finance app that earns permanent space for the right customer. It is not meant to be a universal money manager, and it does not need to be. For Fifth Third account holders who value quick mobile access and are willing to stay attentive when moving money, it delivers recurring value long after the first installation.
Fifth Third: 53 Mobile Banking FAQ
What can I do with the Fifth Third: 53 Mobile Banking app?
Fifth Third: 53 Mobile Banking provides access to many everyday banking services from a smartphone or tablet. After signing in, customers can generally review account balances and transactions, transfer money between eligible accounts, deposit checks with mobile capture, pay bills, manage cards, locate branches or ATMs, and receive account alerts. Available features may depend on your account type, device, location, and Fifth Third eligibility requirements.
Is the Fifth Third: 53 Mobile Banking app safe to use?
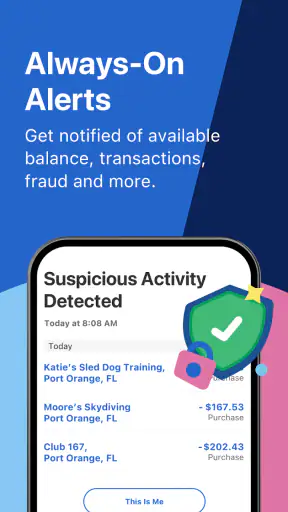
The app is designed with banking security features such as encrypted connections, secure sign-in, device authentication options, fraud monitoring, and alerts for selected account activity. Even so, no banking app eliminates every risk. Install it only from an official app store, keep your operating system updated, avoid public Wi-Fi for sensitive activity, never share verification codes, and contact Fifth Third promptly if you notice suspicious transactions or login activity.
Can I deposit checks through Fifth Third: 53 Mobile Banking?
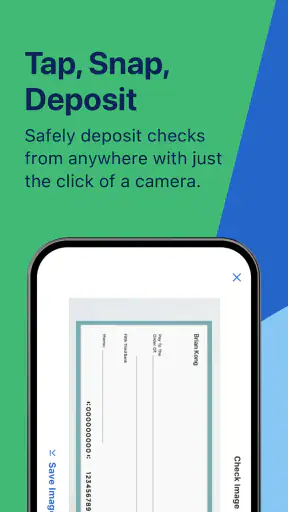
Eligible customers can typically use the app’s mobile check deposit feature by photographing the front and endorsed back of a check, entering the amount, and submitting it for review. Image quality, endorsement wording, deposit limits, account eligibility, and funds availability rules can affect acceptance. Keep the original check safely until the deposit is confirmed and follow the app’s instructions for when it may be destroyed.
Does the app support bill payments and money transfers?
The app generally allows eligible Fifth Third customers to move money between qualifying accounts and manage bill payments without visiting a branch. You may be able to add payees, schedule one-time or recurring payments, and review transfer history. Processing times, cutoff times, transfer limits, fees, and availability can vary, so check the confirmation screen and account terms before scheduling an important payment.
What should I do if I cannot log in or the app is not working?
First, confirm that your internet connection is stable and that you are using the latest version of the app. Restarting the device or reinstalling the official application may resolve temporary problems, but avoid deleting it if you need information that has not synchronized. Use Fifth Third’s official password-recovery and support options, and never rely on unofficial websites or individuals requesting your banking credentials.












